Thursday, December 3, 2009
Jobless claims - 8:30
Full report here
UNEMPLOYMENT INSURANCE WEEKLY CLAIMS REPORT
SEASONALLY ADJUSTED DATA
In the week ending Nov. 28, the advance figure for seasonally adjusted initial claims was 457,000, a decrease of 5,000 from the previous week's revised figure of 462,000. The 4-week moving average was 481,250, a decrease of 14,250 from the previous week's revised average of 495,500.
The advance seasonally adjusted insured unemployment rate was 4.1 percent for the week ending Nov. 21, unchanged from the prior week's unrevised rate of 4.1 percent.
The advance number for seasonally adjusted insured unemployment during the week ending Nov. 21 was 5,465,000, an increase of 28,000 from the preceding week's revised level of 5,437,000. The 4-week moving average was 5,541,500, a decrease of 75,750 from the preceding week's revised average of 5,617,250.
The fiscal year-to-date average for seasonally adjusted insured unemployment for all programs is 5.832 million.
UNADJUSTED DATA
The advance number of actual initial claims under state programs, unadjusted, totaled 460,989 in the week ending Nov. 28, a decrease of 78,263 from the previous week. There were 535,730 initial claims in the comparable week in 2008.
The advance unadjusted insured unemployment rate was 3.6 percent during the week ending Nov. 21, a decrease of 0.3 percentage point from the prior week. The advance unadjusted number for persons claiming UI benefits in state programs totaled 4,787,291, a decrease of 296,052 from the preceding week. A year earlier, the rate was 2.7 percent and the volume was 3,652,990.
Extended benefits were available in Alabama, Alaska, Arizona, California, Colorado, Connecticut, Delaware, the District of Columbia, Florida, Georgia, Idaho, Illinois, Indiana, Kansas, Kentucky, Maine, Massachusetts, Michigan, Minnesota, Missouri, Nevada, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Ohio, Oregon, Pennsylvania, Puerto Rico, Rhode Island, South Carolina, Tennessee, Texas, Vermont, Virginia, Washington, West Virginia, and Wisconsin during the week ending Nov. 14.
Initial claims for UI benefits by former Federal civilian employees totaled 2,269 in the week ending Nov. 21, a decrease of 101 from the prior week. There were 2,330 initial claims by newly discharged veterans, an increase of 368 from the preceding week.
There were 24,523 former Federal civilian employees claiming UI benefits for the week ending Nov. 14, an increase of 1,389 from the previous week. Newly discharged veterans claiming benefits totaled 36,359, an increase of 1,752 from the prior week.
States reported 3,859,553 persons claiming EUC (Emergency Unemployment Compensation) benefits for the week ending Nov. 14, an increase of 265,300 from the prior week. There were 777,393 claimants in the comparable week in 2008. EUC weekly claims include first, second, and third tier activity.
The highest insured unemployment rates in the week ending Nov. 14 were in Puerto Rico (6.1 percent), Oregon (5.9), Alaska (5.5), California (5.2), Nevada (5.2), Michigan (5.1), Pennsylvania (5.0), Wisconsin (5.0), North Carolina (4.8), and Washington (4.7).
The largest increases in initial claims for the week ending Nov. 21 were in California (+14,796), Illinois (+6,168), North Carolina (+5,557), Pennsylvania (+5,285), and Texas (+3,500), while the largest decreases were in Michigan (-1,242), Indiana (-987), Hawaii (-195), Oregon (-167), and the Virgin Islands (-10).


Pre-market - 7:50
Futures up on last nights news about BAC paying back TARP money - an of course a weaker dollar overnight.
DJIA INDEX 10,467.00 28.00
S&P 500 1,111.10 3.20
NASDAQ 100 1,793.75 2.25
Today's economic reports:
Chain Store Sales
Monster Employment Index
ECB Announcement 7:45 AM ET - rate unchanged
Jobless Claims 8:30 AM ET
Productivity and Costs 8:30 AM ET
30-Yr Bond Announcement 9:00 AM ET
ISM Non-Mfg Index 10:00 AM ET
EIA Natural Gas Report 10:30 AM ET
3-Month Bill Announcement 11:00 AM ET
6-Month Bill Announcement 11:00 AM ET
3-Yr Note Announcement 11:00 AM ET
10-Yr Note Announcement 11:00 AM ET
Eric Rosengren Speaks 12:30 PM ET
Money Supply 4:30 PM ET
Today's earnings reports.
Before open:
APWR A-Power Energy Generation Systems, Ltd. Utilities Electric Utilities
CM Canadian Imperial Bank of Commerce Financial Money Center Banks
CUB Cubic Corp. Technology Scientific & Technical Instruments
DLM Del Monte Foods Co. Consumer Goods Processed & Packaged Goods
FLOW Flow International Corp. Industrial Goods Machine Tools & Accessories
MDNU Medical Nutrition USA, Inc. Healthcare Drug Related Products
RSC REX Stores Corp. Services Electronics Stores
STST Argon ST, Inc. Technology Scientific & Technical Instruments
TD Toronto-Dominion Bank Financial Money Center Banks
TOL Toll Brothers Inc. Industrial Goods Residential Construction
TUTR Plato Learning, Inc. Services Business Services
UTIW UTI Worldwide, Inc. Services Air Delivery & Freight Services
After close:
AMSWA American Software, Inc. Technology Application Software
ARST ArcSight, Inc. Technology Business Software & Services
AVAV AeroVironment, Inc. Industrial Goods Aerospace/Defense Products & Services
AVGO Avago Technologies Limited Technology Semiconductor - Broad Line
CMTL Comtech Telecommunications Corp. Technology Communication Equipment
CPWM Cost Plus Inc. Services Department Stores
CRI Carter's, Inc. Consumer Goods Textile - Apparel Clothing
DMND Diamond Foods, Inc. Consumer Goods Processed & Packaged Goods
LAVA Magma Design Automation Inc. Technology Business Software & Services
LQDT Liquidity Services, Inc. Technology Internet Software & Services
MENT Mentor Graphics Corp. Technology Technical & System Software
MRVL Marvell Technology Group Ltd. Technology Semiconductor - Integrated Circuits
NOVL Novell Inc. Technology Security Software & Services
OHB Orleans Homebuilders Inc. Industrial Goods Residential Construction
ULTA Ulta Salon, Cosmetics & Fragrance, Inc. Services Personal Services
XETA XETA Technologies Inc. Technology Communication Equipment
Wednesday, December 2, 2009
Market wrap - 4:15
Mixed day in the market, not much happening.
Dow 10,453 -19 -0.18%
Nasdaq 2,185 9 0.42%
S&P 500 1,109 0 0.03%
GlobalDow 1,984 +6 +0.29%
Gold 1,213 +13 +1.07%
Oil 76.62 -1.77 -2.26%

Beige Book - 2:00
Full report here
Prepared at the Federal Reserve Bank of New York and based on information collected on or before November 20, 2009. This document summarizes comments received from businesses and other contacts outside the Federal Reserve and is not a commentary on the views of Federal Reserve officials.
Reports from the twelve Federal Reserve Districts indicate that economic conditions have generally improved modestly since the last report. Eight Districts indicated some pickup in activity or improvement in conditions, while the remaining four--Philadelphia, Cleveland, Richmond, and Atlanta--reported that conditions were little changed and/or mixed.
Consumer spending was reported to have picked up moderately since the last report, for both general merchandise and vehicles; a number of Districts noted relatively robust sales of used autos. Most Districts indicated that non-auto retailers were holding lean inventories going into the holiday season. Tourism activity varied across Districts. Manufacturing conditions were said to be, on balance, steady to moderately improving across most of the country, while conditions in the nonfinancial service sector generally strengthened somewhat, though with some variation across Districts and across industries. Residential real estate conditions were somewhat improved from very low levels, on balance, led by the lower end of the market. Most Districts reported some pickup in home sales, though prices were generally said to be flat or declining modestly; residential construction was characterized as weak, but some Districts did note some pickup in activity. Commercial real estate markets and construction activity were depicted as very weak and, in many cases, deteriorating.
Financial institutions generally reported steady to weaker loan demand, continued tight credit standards, and steady or deteriorating loan quality. In the agricultural sector, the fall harvest was delayed in the eastern half of the nation due to excessively wet conditions during October and early November. Most energy-producing Districts noted a slight uptick in activity in the sector since the last report. Labor market conditions remained weak since the last report, though there were signs of stabilization and scattered signs of improvement. While some Districts reported upward pressure on commodity prices, they saw little or no indication of upward wage pressures or of any significant increase in prices of finished goods.
Consumer Spending and Tourism
Consumer spending strengthened since the last report, with sales of both general merchandise and autos improving across much of the country. Non-auto sales were reported to have picked up in the New York, Philadelphia, Cleveland, Richmond, Atlanta, Kansas City, and San Francisco Districts; sales were described as steady or mixed in the Boston, Chicago, Minneapolis, and Dallas Districts. St. Louis described retail sales as below expectations and down from a year earlier. Auto sales generally improved since the last report, in some cases rebounding from a brief dip after the "cash-for-clunkers" program ended. Increased vehicle sales were reported from New York, Philadelphia, Richmond, Chicago, St. Louis, and Dallas, while sales were described as flat or mixed in the Cleveland, Minneapolis, Kansas City, and San Francisco Districts. A number of Districts reported that used vehicles have been selling better than new ones.
Most Districts also noted that retailers were holding leaner inventories this holiday season, though some indicate that retailers have recently become more optimistic about the holiday-season outlook. Auto dealers' inventories, largely depleted during the cash-for-clunkers program, have been or are being rebuilt.
Tourism was mixed across those Districts reporting. Travel and tourism--especially leisure travel--was described as robust or improved in the New York, Dallas, and San Francisco Districts. Atlanta and Kansas City characterized tourism as sluggish, while Richmond and Minneapolis described it as mixed; Richmond noted that tourism has been adversely affected by severe and damaging coastal storms, while Kansas City characterized the outlook as "grim." New York indicated that business travel remained sluggish, but Minneapolis and Dallas note a slight pickup.
Nonfinancial Services
Activity in the service sector generally picked up since the last report, though results were mixed across Districts and across service industries. New York and Philadelphia reported that service-sector activity overall remained steady to up slightly, while St. Louis noted expanding activity. The information technology industry was reported to be showing improvement in the Boston, Minneapolis, and Kansas City Districts. A pickup in activity at staffing firms was reported by Boston and Dallas, whereas New York noted that activity remained sluggish. Strength in health services was noted in the Boston and Richmond Districts. Shipping activity was characterized as flat in the Cleveland, Atlanta, and Kansas City District, while Dallas reports some gain; however, Dallas and Atlanta both noted particular weakness in rail shipping activity. Professional and business support firms reportedly registered some improvement in the St. Louis and Minneapolis Districts but flat to declining activity in Richmond and San Francisco.
Manufacturing
Most Districts reported mixed to moderately improving manufacturing conditions since the last report. New York, Philadelphia, Cleveland, Minneapolis, Kansas City, and San Francisco all noted modest increases in manufacturing activity within their Districts. Manufacturing conditions in the Boston and Dallas Districts were characterized as mixed, with some improvement noted for biopharmaceuticals companies in Boston and high-tech manufacturing firms in Dallas. By contrast, Richmond and Chicago both reported that manufacturing activity had leveled off since the last report, while activity continued to decline in the Atlanta and St. Louis Districts, although at a somewhat slower pace than the last report. Tighter credit limited the ability of customers to place new orders in the Richmond District, while in the Chicago District, contacts noted a slowdown in the restocking of inventories. Increases in activity related to the transportation industry were cited in the Chicago, St. Louis, Cleveland, and Kansas City Districts, although such activity was mixed in the Dallas District and reported as declining in the San Francisco District. Several Districts noted an uptick in food-related production.
Many Districts reported that their contacts were optimistic about the near-term outlook. Manufacturers in the Boston, New York, Philadelphia, Atlanta, Minneapolis, and Kansas City Districts expected business conditions to improve in the coming months, while producers in the Cleveland District expressed uncertainty about near-term conditions. The outlook in the Dallas District was mixed, with most manufacturers expressing cautious optimism about the near term and construction-related manufacturers expressing pessimism about the future largely due to expectations of prolonged weakness in commercial real estate.
Real Estate and Construction
Home sales and construction activity improved across much of the nation, though prices were generally said to be flat or still declining somewhat. A majority of Districts reported that the lower-priced segment of the housing market has outperformed the high end. Increases in sales activity were reported in the Boston, Cleveland, Richmond, Atlanta, Chicago, Minneapolis, Kansas City, Dallas, and San Francisco Districts, whereas sales were described as steady or mixed in the New York and Philadelphia Districts. Multifamily housing markets deteriorated further in the New York and Chicago Districts. More broadly, a number of eastern Districts reported continued declines in home prices--specifically, Boston, New York, Philadelphia, and Richmond. In contrast, prices were said to have firmed somewhat in the Dallas and San Francisco Districts and stabilized in the Chicago and Kansas City Districts. Most reports maintained that the lower end of the market has outperformed the higher end: New York, Philadelphia, Richmond, Atlanta, Minneapolis, and Kansas City all noted relative weakness at the high end of the market, with relative strength at the lower end; in most cases, this strength was largely attributed to the homebuyer tax credit (which was recently reinstated and expanded to include existing owners).
Despite the firming in sales, the level of new residential construction activity was generally characterized as weak, though recent trends have been mixed--Atlanta, Kansas City, and Dallas noted some pickup in home construction, whereas the Chicago and St. Louis Districts reported declines. Residential construction was described as flat or stabilizing by Cleveland, Minneapolis, and San Francisco.
Commercial real estate conditions were widely characterized as weak and, in many cases, deteriorating further. Market conditions were reported to have weakened in virtually all Districts, with rising vacancy rates, downward pressure on rents, and little, if any, new development. Expectations for 2010 were also quite low. Boston characterized the commercial real estate outlook as "bleak," Dallas noted that construction was at "historically low levels," and Kansas City described the sector as "distressed." Still, some Districts noted scattered signs of encouragement: Cleveland and Chicago referenced public-works projects as a source of increased business, Richmond noted signs of increased leasing activity from the health and education sectors, Atlanta indicated a modest pickup in new development projects, Minneapolis noted some recently started hotel and retail development, and San Francisco cited slight improvement in availability of financing for new development.
Banking and Finance
Banks reported steady to softer conditions in most Districts. Loan demand was said to have weakened in the New York, Philadelphia, Cleveland, St. Louis, Kansas City, and Dallas Districts. New York noted particular weakness in demand for home mortgage loans, whereas Richmond and St. Louis reported this to be the strongest segment of late. For the most part, the weakness appears to have been concentrated in the commercial sector, though Boston and Chicago reported some pickup in commercial real estate lending--largely refinancing. Credit quality showed signs of deteriorating in the New York, Philadelphia, Dallas, and San Francisco Districts but was described as stable or mixed in Cleveland, Chicago, and Kansas City, with Chicago reporting some improvement outside of commercial real estate. Increasingly tight credit standards were reported in the New York, Richmond, Chicago, St. Louis, Dallas, and San Francisco--largely on commercial loans.
Agriculture and Natural Resources
Excessively wet conditions during October and early November were reported in a number of Districts. As a result, the fall harvest was delayed in many parts of the Richmond, Atlanta, Chicago, St. Louis, Minneapolis, and Kansas City Districts. Flooding from Tropical Storm Ida and a November "nor'easter" damaged crops and delayed planting throughout the Richmond District, and Virginia health officials closed fishing in all Chesapeake Bay tributaries and temporarily banned the harvesting of shellfish due to potential storm water contamination. By contrast, rainfall in the Dallas District helped alleviate drought conditions experienced in many parts of the region. Contacts in the Chicago, Minneapolis, and Kansas City Districts noted that corn and soybean prices rallied over the past month, although a wide variation in margins was expected for crop farms due to differences in input costs. Losses for livestock operations occurred in the Chicago and Kansas City Districts.
Most energy-producing Districts reported a slight uptick in activity in extraction industries since the last report. Contacts in the Cleveland, Atlanta, Dallas, Minneapolis, Kansas City, and San Francisco Districts noted steady to increasing oil and natural gas production within their regions, albeit from low levels of production observed earlier this year. Contacts in the Cleveland District also reported that a sharp decline in coal production had leveled out since the last report. In general, oil prices increased somewhat, while reports on the price of natural gas were mixed due in large part to differences in inventory levels across Districts. Mining activity in the Minneapolis District increased.
Employment, Wages, and Prices
Labor market conditions remained weak since the last report, with further layoffs, sluggish hiring, and high levels of unemployment in most Districts. However, contacts in the Atlanta, Cleveland, and Richmond Districts reported that the pace of job cuts generally slowed in their regions, and most contacts in the Dallas District reported stable employment levels. Despite generally weak employment conditions, some signs of improvement were noted. For example, contacts in Boston reported that they were beginning to hire and reverse pay cuts or freezes that were implemented earlier in the year, and contacts in the St. Louis District reported that the service sector had started to expand recently. Expectations for the holiday season were mixed across Districts, with contacts in the New York and Dallas Districts reporting lighter-than-normal seasonal hiring and/or increases in the hours of existing employees, as opposed to hiring temporary workers, to meet the seasonal demand. On the other hand, most retailers in the Richmond District have hired the usual number of seasonal workers this year.
Districts generally reported little or no upward wage pressures, while some Districts noted upward pressure in commodity prices, and most Districts reported stable selling prices. Wages were largely reported to be holding steady in the Boston, Cleveland, Richmond, Chicago, Minneapolis, Kansas City, Dallas, and San Francisco Districts. Most Districts reported stable prices overall, although some reported higher input prices, largely for energy and other commodities used in production, with a limited ability to raise selling prices. Prices were reported as moderately lower in the Kansas City District, and downward price pressures were cited for some professional services and intermodal transportation firms in the Dallas District. Some makers of food products and chemicals in the Philadelphia District reported raising prices, and the prices of computer memory chips continued to firm in the San Francisco District. Retailers in several Districts indicated that they have managed inventory levels in an effort to prevent the steep price discounting that occurred last year, however, some promotional price discounting is expected through the holiday season.
Pre-market - Wednesday, December 2
Futures just plain flat today. Not worth posting - just flat.
Today's economic news:
MBA Purchase Applications 7:00 AM ET
Challenger Job-Cut Report 7:30 AM ET
ADP Employment Report 8:15 AM ET
Tim Geithner Speaks 9:30 AM ET
EIA Petroleum Status Report 10:30 AM ET
Beige Book 2:00 PM ET
Before open:
CHRS Charming Shoppes Inc. Services Apparel Stores
DSGX Descartes Systems Group Inc. Technology Business Software & Services
GIII G-III Apparel Group, Ltd. Consumer Goods Textile - Apparel Clothing
JOSB Jos. A Bank Clothiers Inc. Services Apparel Stores
PTRY Pantry Inc. Services Grocery Stores
SYNO Synovis Life Technologies Inc. Healthcare Medical Appliances & Equipment
After close:
ARO Aeropostale Inc. Services Apparel Stores
ATCO American Technology Corp. Technology Diversified Electronics
CWST Casella Waste Systems Inc. Industrial Goods Waste Management
DDMX Dynamex Inc. Services Trucking
JAS Jo-Ann Stores, Inc. Services Specialty Retail, Other
PSS Collective Brands, Inc. Services Apparel Stores
SEAC SeaChange International Inc. Technology Processing Systems & Products
SIGM Sigma Designs, Inc. Technology Semiconductor - Specialized
SNPS Synopsys Inc. Technology Technical & System Software
Tuesday, December 1, 2009
Market wrap - 6:30
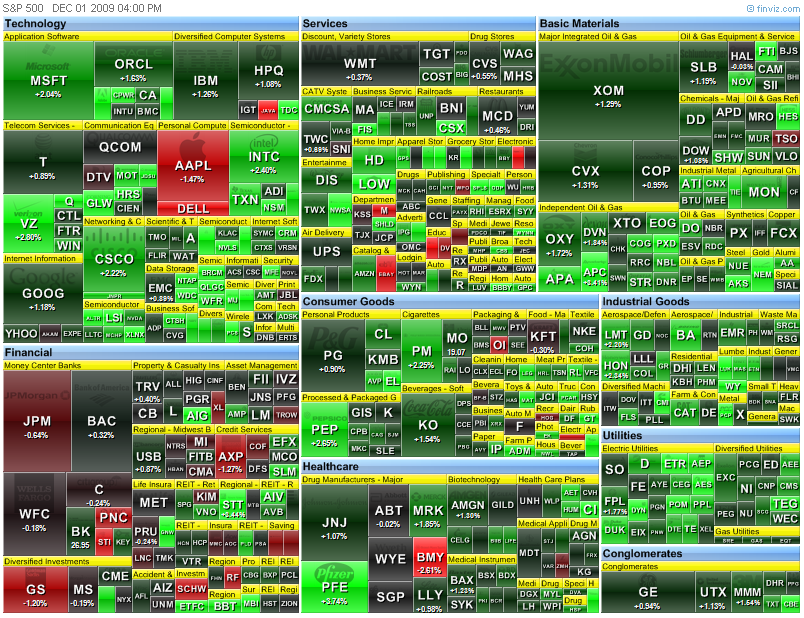
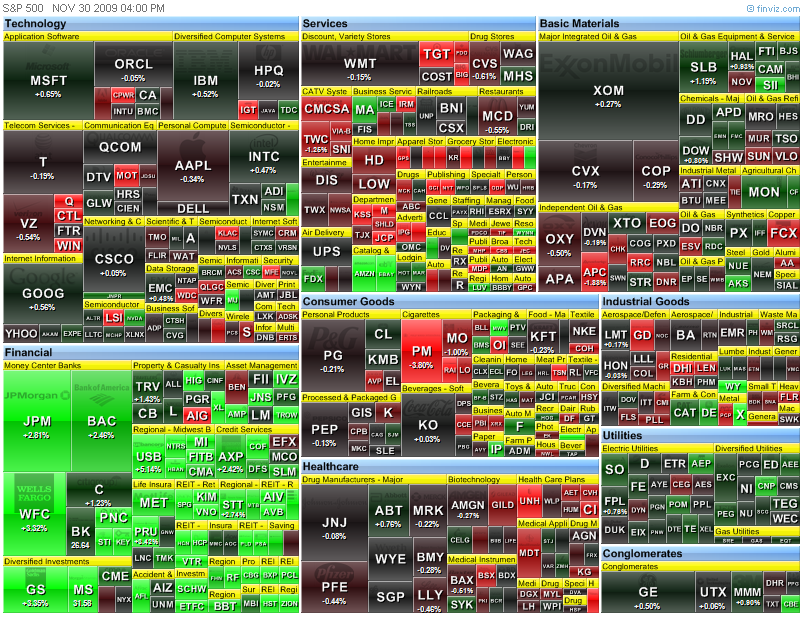
Just another day in the casino. Large gap up this morning, traded a bit higher during the day, only to sell off a bit in the last hour and a half. Notice GS & AAPL, the leaders since March.
Dow 10,472 127 1.23%
Nasdaq 2,176 31 1.46%
S&P 500 1,109 +13 +1.21%
Gold 1,200 +18 +1.51%
Oil 77.93 +1.09 +1.41%
ISM manufacturing - 10:00 - late because link did not work
Full report here
November 2009 Manufacturing ISM Report On Business®
PMI at 53.6%
DO NOT CONFUSE THIS NATIONAL REPORT with the various regional purchasing reports released across the country. The national report's information reflects the entire United States, while the regional reports contain primarily regional data from their local vicinities. Also, the information in the regional reports is not used in calculating the results of the national report. The information compiled in this report is for the month of November 2009.
New Orders, Production and Employment Growing
Inventories Contracting
Supplier Deliveries Slower
(Tempe, Arizona) — Economic activity in the manufacturing sector expanded in November for the fourth consecutive month, and the overall economy grew for the seventh consecutive month, say the nation's supply executives in the latest Manufacturing ISM Report On Business®.
The report was issued today by Norbert J. Ore, CPSM, C.P.M., chair of the Institute for Supply Management™ Manufacturing Business Survey Committee. "The manufacturing sector grew for the fourth consecutive month in November. While the rate of growth slowed when compared to October, the signs are still encouraging for continuing growth as both new orders and production are still at very positive levels, and the Prices Index fell 10 points, signaling less inflationary pressure on manufacturers' costs. Overall, the recovery in manufacturing is continuing, but many are still struggling based on their comments."
PERFORMANCE BY INDUSTRY
In November, 12 of the 18 manufacturing industries reported growth. The industries — listed in order — are: Apparel, Leather & Allied Products; Printing & Related Support Activities; Petroleum & Coal Products; Miscellaneous Manufacturing; Electrical Equipment, Appliances & Components; Transportation Equipment; Chemical Products; Computer & Electronic Products; Food, Beverage & Tobacco Products; Paper Products; Fabricated Metal Products; and Machinery. The five industries reporting contraction in November are: Wood Products; Furniture & Related Products; Nonmetallic Mineral Products; Primary Metals; and Plastics & Rubber Products.
WHAT RESPONDENTS ARE SAYING ...
* "Becoming concerned about the value of the U.S. dollar." (Apparel, Leather & Allied Products)
* "Low value of the dollar driving commodity costs higher." (Food, Beverage & Tobacco Products)
* "Demand from automotive manufacturers remains strong and building." (Fabricated Metal Products)
* "Capital construction seems to be picking up, and we are seeing more jobs that are bid out." (Electrical Equipment, Appliances & Components)
* "Steady increase in business." (Primary Metals)
 COMMODITIES REPORTED UP/DOWN IN PRICE and IN SHORT SUPPLY
Commodities Up in Price
Aluminum (5); Copper (6); Copper Based Products (5); Natural Gas (2); Oil; and Steel (5).
Commodities Down in Price
No commodities are reported down in price.
Commodities in Short Supply
Electronic Components is the only commodity reported in short supply.
Note: The number of consecutive months the commodity is listed is indicated after each item.
PMI
Manufacturing growth decelerated in November as the PMI registered 53.6 percent, a decrease of 2.1 percentage points when compared to October's reading of 55.7 percent. This continues the recovery in the sector, but at a slower rate of growth. A reading above 50 percent indicates that the manufacturing economy is generally expanding; below 50 percent indicates that it is generally contracting.
A PMI in excess of 41.2 percent, over a period of time, generally indicates an expansion of the overall economy. Therefore, the PMI indicates growth for the seventh consecutive month in the overall economy, as well as expansion in the manufacturing sector for the fourth consecutive month. Ore stated, "The past relationship between the PMI and the overall economy indicates that the average PMI for January through November (45.4 percent) corresponds to a 1.3 percent increase in real gross domestic product (GDP). However, if the PMI for November (53.6 percent) is annualized, it corresponds to a 3.9 percent increase in real GDP annually."
THE LAST 12 MONTHS

COMMODITIES REPORTED UP/DOWN IN PRICE and IN SHORT SUPPLY
Commodities Up in Price
Aluminum (5); Copper (6); Copper Based Products (5); Natural Gas (2); Oil; and Steel (5).
Commodities Down in Price
No commodities are reported down in price.
Commodities in Short Supply
Electronic Components is the only commodity reported in short supply.
Note: The number of consecutive months the commodity is listed is indicated after each item.
PMI
Manufacturing growth decelerated in November as the PMI registered 53.6 percent, a decrease of 2.1 percentage points when compared to October's reading of 55.7 percent. This continues the recovery in the sector, but at a slower rate of growth. A reading above 50 percent indicates that the manufacturing economy is generally expanding; below 50 percent indicates that it is generally contracting.
A PMI in excess of 41.2 percent, over a period of time, generally indicates an expansion of the overall economy. Therefore, the PMI indicates growth for the seventh consecutive month in the overall economy, as well as expansion in the manufacturing sector for the fourth consecutive month. Ore stated, "The past relationship between the PMI and the overall economy indicates that the average PMI for January through November (45.4 percent) corresponds to a 1.3 percent increase in real gross domestic product (GDP). However, if the PMI for November (53.6 percent) is annualized, it corresponds to a 3.9 percent increase in real GDP annually."
THE LAST 12 MONTHS
Pending home sales - 10:00
Full report here
Pending home sales have risen for nine months in a row, a first for the series of the index since its inception in 2001, according to the National Association of Realtors®.
The Pending Home Sales Index,* a forward-looking indicator based on contracts signed in October, increased 3.7 percent to 114.1 from 110.0 in September, and is 31.8 percent above October 2008 when it was 86.6. The rise from a year ago is the biggest annual increase ever recorded for the index, which is at the highest level since March 2006 when it was 115.2.
Lawrence Yun, NAR chief economist, said home sales are experiencing a pendulum swing. “Keep in mind that housing had been underperforming over most of the past year. Based on the demographics of our growing population, existing-home sales should be in the range of 5.5 million to 6.0 million annually, but we were well below the 5-million mark before the home buyer tax credit stimulus,” he said. “This means the tax credit is helping unleash a pent-up demand from a large pool of financially qualified renters, much more than borrowing sales from the future.
The PHSI in the Northeast surged 19.9 percent to 100.2 in October and is 44.2 percent above a year ago. In the Midwest the index rose 11.6 percent to 109.6 and is 36.6 percent higher than October 2008. Pending home sales in the South increased 5.4 percent to an index of 115.4, which is 31.6 percent above a year ago. In the West the index fell 11.2 percent to 127.7 but is 21.9 percent above October 2008.
Yun cautioned that home sales could dip in the months ahead. “The expanded tax credit has only been available for the past three weeks, but the time between when buyers start looking at homes until they close on a sale can take anywhere from three to five months. Given the lag time, we could see a temporary decline in closed existing-home sales from December until early spring when we get another surge, but the weak job market remains a major concern and could slow the recovery process.
“Still, as inventories continue to decline and balance is gradually restored between buyers and sellers, we should reach self-sustaining housing conditions and firming home prices in most areas around the middle of 2010. That would mean broad wealth stabilization for the vast number of middle-class families,” Yun said.
The National Association of Realtors®, “The Voice for Real Estate,” is America’s largest trade association, representing 1.2 million members involved in all aspects of the residential and commercial real estate industries.
Construction spending - 10:00
Full report here
OCTOBER 2009 CONSTRUCTION AT $910.8 BILLION ANNUAL RATE
The U.S. Census Bureau of the Department of Commerce announced today that construction spending during October 2009 was estimated at a seasonally adjusted annual rate of $910.8 billion, nearly the same as (±1.6%)* the revised September estimate of $910.4 billion. The October figure is 14.4 percent (±1.6%) below the October 2008 estimate of $1,064.1 billion. During the first 10 months of this year, construction spending amounted to $794.0 billion, 12.6 percent (±1.1%) below the $908.9 billion for the same period in 2008.
PRIVATE CONSTRUCTION
Spending on private construction was at a seasonally adjusted annual rate of $589.0 billion, 0.3 percent (±1.1%)* above the revised September estimate of $587.2 illion. Residential construction was at a seasonally adjusted annual rate of $250.3 billion in October, 4.4 percent (±1.3%) above the revised September estimate of $239.7 billion. Nonresidential construction was at a seasonally adjusted annual rate of $338.6 billion in October, 2.5 percent (±1.1%) below the revised September estimate of $347.5 billion.
PUBLIC CONSTRUCTION
In October, the estimated seasonally adjusted annual rate of public construction spending was $321.8 billion, 0.4 percent (±2.4%)* below the revised September estimate of $323.2 billion. Educational construction was at a seasonally adjusted
annual rate of $85.7 billion, 1.1 percent (±2.9%)* above the revised September estimate of $84.7 billion. Highway construction was at a seasonally adjusted annual rate of $87.2 billion, 0.3 percent (±6.6%)* below the revised September estimate of $87.4 billion.
Pre-market - Tuesday - December 1
Futures up on a falling dollar
DJIA INDEX 10,400.00 66.00
S&P 500 1,102.80 8.00
NASDAQ 100 1,781.00 13.50
Today's economic reports:
Motor Vehicle Sales
ICSC-Goldman Store Sales 7:45 AM ET
Redbook 8:55 AM ET
ISM Mfg Index 10:00 AM ET
Construction Spending 10:00 AM ET
Pending Home Sales Index 10:00 AM ET
4-Week Bill Auction 11:30 AM ET
Today's earnings reports:
Before open:
BECN Beacon Roofing Supply Inc. Services Building Materials Wholesale
GIGM GigaMedia Ltd. Technology Internet Software & Services
ISLE Isle of Capri Casinos Inc. Services Resorts & Casinos
LDR Landauer Inc. Services Research Services
NPD China Nepstar Chain Drugstore Ltd. Services Drug Stores
SPLS Staples, Inc. Services Specialty Retail, Other
THO Thor Industries Inc. Consumer Goods Recreational Vehicles
UTI Universal Technical Institute Inc. Services Education & Training Services
After close:
CFI Culp Inc. Industrial Goods Textile Industrial
CPRT Copart Inc. Services Auto Dealerships
GAME Shanda Games Limited Services Entertainment - Diversified
LTXC LTX-Credence Corporation Technology Semiconductor Equipment & Materials
SNDA Shanda Interactive Entertainment Ltd. Technology Internet Software & Services
Market wrap - a day late -
Dow 10,345 35 0.34%
Nasdaq 2,145 6 0.29%
S&P 500 1,096 4 0.38%
GlobalDow1,961 +21 +1.07%
Gold 1,183 8 0.64%
Oil 78.05 0.83 1.07%
Monday, November 30, 2009
Chicago PMI - 9:45
 Highlights
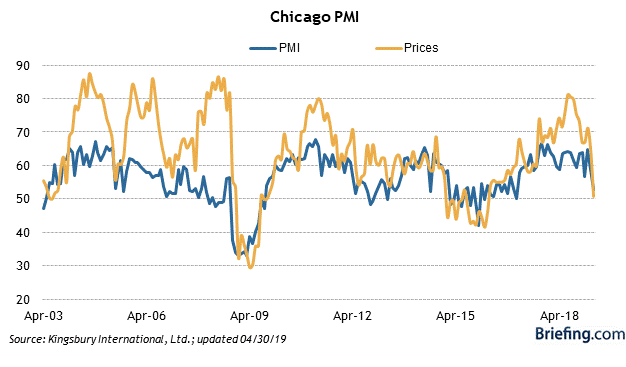
* The Chicago PMI index jumped over the 50 point threshold for the first time since September 2008 as the index grew to 54.2 in October. The consensus expected the index to increase slightly to 49.0 from 46.1 and remain in the contraction phase.
* The production index increased to 63.9 from 47.2 and orders rose to 61.4 from 46.3.
* Inventories continued to contract and have gotten worse over the last month as the index declined to 32.2 from 38.9.
* The only other sector that continued to contract was employment, which declined to 38.3 from 38.8.
* Other components of the index showed the manufacturing sector strengthening including order backlogs, which increased to 41.9 from 36.7 and prices paid, which declined to 48.6 from 51.3.
Key Factors
* The entire index showed signs of a sustainable expansionary cycle.
* Unlike last month's national index, where production grew on the anticipation of new orders that never came in, production and new orders posted strong growth and entered an expansionary phase in the Chicago region.
Big Picture
* The Chicago PMI has little overall economic value, and is only watched by the financial markets because it is usually released one day in advance of the similar national ISM manufacturing survey. A significant move in this regional survey will therefore sometimes be seen as having predictive value for the ISM index.
Pre-market - Monday, November 30, 2009
Futures down slightly on the Dubai worries.
DJIA INDEX 10,280.00 -12.00
S&P 500 1,087.70 -1.80
NASDAQ 100 1,757.25 -2.00
Today's economic reports:
Chicago PMI9:45 AM ET
4-Week Bill Announcement 11:00 AM ET
3-Month Bill Auction 11:30 AM ET
6-Month Bill Auction 11:30 AM ET
Farm Prices 3:00 PM ET
Today's earnings reports.
Before open:
NRGY Inergy, L.P. Services Specialty Retail, Other
PATR Patriot Transportation Holding Inc. Services Trucking
TLVT Telvent Git S.A. Technology Computer Based Systems
UNFY Unify Corp. Technology Business Software & Services
After close:
GES Guess? Inc. Services Apparel Stores
LTON Linktone Ltd. Technology Wireless Communications
OVTI OmniVision Technologies Inc. Technology Semiconductor - Integrated Circuits
SNS Steak n Shake Co. Services Restaurants
SOFOD Sonic Foundry Inc. Technology Application Software
ZOLT Zoltek Companies Inc. Industrial Goods Industrial Electrical Equipment
Friday, November 27, 2009
Market wrap - 1:15
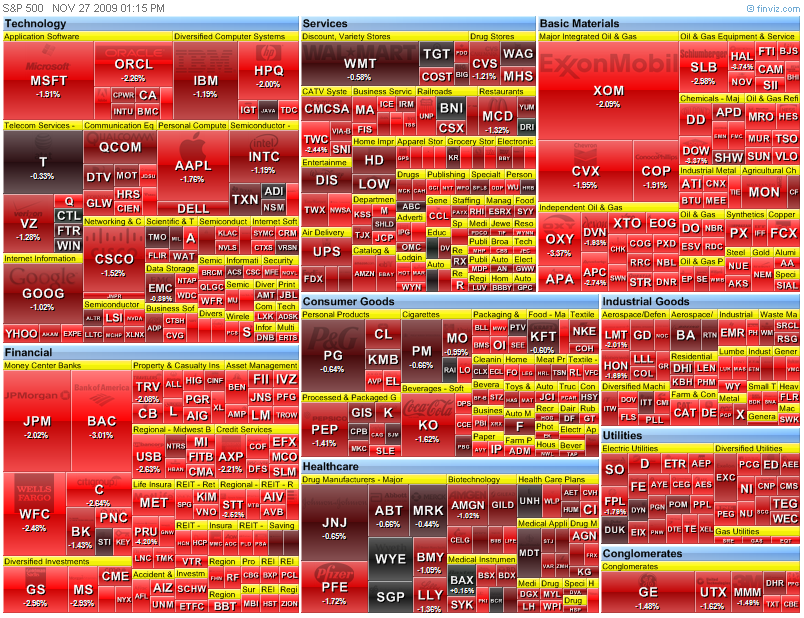
Not as bad as it could have been, but are we out of the woods now? Let's see what happens Monday when everyone is back, and the exposure to Dubai has been digested.
Dow 10,310 -154 -1.48%
Nasdaq 2,138 -38 -1.73%
S&P 500 1,091 -19 -1.72%
Gold 1,176 -13 -1.10%
Oil 75.76 -2.19 -2.81%

Pre-market - 8:15
Futures down big, but off the lows overnight on the news out of Dubai and their debt problem.
DJIA INDEX 10,222.00 -220.00
S&P 500 1,079.10 -29.80
NASDAQ 100 1,745.50 -48.75
Today's economic calendar:
None - Market closes at 1:00
Today's earnings reports:
Before open:
FRO Frontline Ltd. Services Shipping
SFL Ship Finance International Limited Services Shipping
After close = none
Wednesday, November 25, 2009
Jobless claims - 8:30
Full report here
UNEMPLOYMENT INSURANCE WEEKLY CLAIMS REPORT
SEASONALLY ADJUSTED DATA
In the week ending Nov. 21, the advance figure for seasonally adjusted initial claims was 466,000, a decrease of 35,000 from the previous week's revised figure of 501,000. The 4-week moving average was 496,500, a decrease of 16,500 from the previous week's revised average of 513,000.
The advance seasonally adjusted insured unemployment rate was 4.1 percent for the week ending Nov. 14, a decrease of 0.2 percentage point from the prior week's unrevised rate of 4.3 percent.
The advance number for seasonally adjusted insured unemployment during the week ending Nov. 14 was 5,423,000, a decrease of 190,000 from the preceding week's revised level of 5,613,000. The 4-week moving average was 5,613,750, a decrease of 98,500 from the preceding week's revised average of 5,712,250.
The fiscal year-to-date average for seasonally adjusted insured unemployment for all programs is 5.866 million.
UNADJUSTED DATA
The advance number of actual initial claims under state programs, unadjusted, totaled 543,926 in the week ending Nov. 21, an increase of 68,080 from the previous week. There were 609,138 initial claims in the comparable week in 2008.
The advance unadjusted insured unemployment rate was 3.8 percent during the week ending Nov. 14, an increase of 0.1 percentage point from the prior week. The advance unadjusted number for persons claiming UI benefits in state programs totaled 5,070,712, an increase of 187,642 from the preceding week. A year earlier, the rate was 2.8 percent and the volume was 3,782,040.
Extended benefits were available in Alabama, Alaska, Arizona, California, Colorado, Connecticut, Delaware, the District of Columbia, Florida, Georgia, Idaho, Illinois, Indiana, Kansas, Kentucky, Maine, Massachusetts, Michigan, Minnesota, Missouri, Nevada, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Ohio, Oregon, Pennsylvania, Puerto Rico, Rhode Island, South Carolina, Tennessee, Texas, Vermont, Virginia, Washington, West Virginia, and Wisconsin during the week ending Nov. 7.
Initial claims for UI benefits by former Federal civilian employees totaled 2,346 in the week ending Nov. 14, an increase of 45 from the prior week. There were 2,026 initial claims by newly discharged veterans, a decrease of 408 from the preceding week.
There were 22,941 former Federal civilian employees claiming UI benefits for the week ending Nov. 7, a decrease of 1,962 from the previous week. Newly discharged veterans claiming benefits totaled 34,598, a decrease of 301 from the prior week.
States reported 3,639,036 persons claiming EUC (Emergency Unemployment Compensation) benefits for the week ending Nov. 7, an increase of 16,370 from the prior week. There were 766,565 claimants in the comparable week in 2008. EUC weekly claims include both first and second tier activity.
The highest insured unemployment rates in the week ending Nov. 7 were in Puerto Rico (6.2 percent), Oregon (5.5), Alaska (5.1), Nevada (5.1), Pennsylvania (4.9), Wisconsin (4.9), Arkansas (4.7), California (4.7), Michigan (4.6), North Carolina (4.6), and Washington (4.6).
The largest increases in initial claims for the week ending Nov. 14 were in Florida (+1,313), Indiana (+607), Hawaii (+278), and North Dakota (+81), while the largest decreases were in California (-7,987), Texas (-4,710), Pennsylvania (-4,321), Wisconsin (-2,716), and Ohio (-2,486).
More at link with formatted tables
Pre-market - late - 9:25
Futures higher after a good job number.
DJIA INDEX 10,437.00 32.00
S&P 500 1,106.90 3.80
NASDAQ 100 1,793.50
Today's economic calendar:
MBA Purchase Applications 7:00 AM ET
Durable Goods Orders 8:30 AM ET
Personal Income and Outlays 8:30 AM ET
Jobless Claims 8:30 AM ET
Consumer Sentiment 9:55 AM ET
New Home Sales 10:00 AM ET
EIA Petroleum Status Report 10:30 AM ET
3-Month Bill Announcement 11:00 AM ET
6-Month Bill Announcement 11:00 AM ET
EIA Natural Gas Report 12:00 PM ET
7-Yr Note Auction 1:00 PM ET
Today's earnings reports:
Before open:
CONN Conns Inc. Services Electronics Stores
DE Deere & Co. Industrial Goods Farm & Construction Machinery
JRJC China Finance Online Co. Ltd. Technology Internet Information Providers
TIF Tiffany & Co. Services Jewelry Stores
After close:
APWR A-Power Energy Generation Systems, Ltd. Utilities Electric Utilities
Tuesday, November 24, 2009
GDP - 8:30
Full report here
Real gross domestic product -- the output of goods and services produced by labor and property located in the United States -- increased at an annual rate of 2.8 percent in the third quarter of 2009, (that is, from the second quarter to the third quarter), according to the "second" estimate released by the Bureau of Economic Analysis. In the second quarter, real GDP decreased 0.7 percent.
The GDP estimate released today is based on more complete source data than were available for the "advance" estimate issued last month. In the advance estimate, the increase in real GDP was 3.5 percent (see "Revisions" on page 3).
The increase in real GDP in the third quarter primarily reflected positive contributions from personal consumption expenditures (PCE), exports, private inventory investment, federal government spending, and residential fixed investment that were partly offset by a negative contribution from nonresidential fixed investment. Imports, which are a subtraction in the calculation of GDP, increased.
The upturn in real GDP in the third quarter primarily reflected upturns in PCE, in private inventory investment, in exports, and in residential fixed investment and a smaller decrease in nonresidential fixed investment that were partly offset by an upturn in imports, a downturn in state and local government spending, and a deceleration in federal government spending.
Pre-market - Tuesday, November 24, 2009
Futures up a tad before GDP report.
DJIA INDEX 10,437.00 15.00
S&P 500 1,106.70 2.90
NASDAQ 100 1,792.75 1.50
Today's economic reports:
ICSC-Goldman Store Sales 7:45 AM ET
GDP 8:30 AM ET
Corporate Profits 8:30 AM ET
Redbook 8:55 AM ET
S&P Case-Shiller HP I9:00 AM ET
Consumer Confidence 10:00 AM ET
State Street Investor Confidence Index 10:00 AM ET
4-Week Bill Auction 11:30 AM ET
5-Yr Note Auction 1:00 PM ET
FOMC Minutes 2:00 PM ET
Today's earnings reports:
Before open:
AEO American Eagle Outfitters, Inc. Services Apparel Stores
AHCI Allied Healthcare International Inc. Healthcare Home Health Care
AMWD American Woodmark Corp. Industrial Goods Lumber, Wood Production
AVNR Avanir Pharmaceuticals Healthcare Drug Manufacturers - Other
BGP Borders Group, Inc. Services Specialty Retail, Other
BKS Barnes & Noble, Inc. Services Specialty Retail, Other
BWS Brown Shoe Co. Inc. Consumer Goods Textile - Apparel Footwear & Accessories
CBRL Cracker Barrel Old Country Store, Inc. Services Restaurants
DAKT Daktronics Inc. Industrial Goods Industrial Electrical Equipment
DHT DHT Maritime, Inc. Services Shipping
DLIA dELiA*s, Inc. Services Catalog & Mail Order Houses
DLTR Dollar Tree Inc. Services Discount, Variety Stores
DSW DSW Inc. Services Apparel Stores
EV Eaton Vance Corp. Financial Asset Management
FRED Fred's Inc. Services Discount, Variety Stores
GCO Genesco Inc. Services Apparel Stores
GIGM GigaMedia Ltd. Technology Internet Software & Services
HI Hillenbrand, Inc. Services Personal Services
HNZ HJ Heinz Co. Consumer Goods Food - Major Diversified
HRL Hormel Foods Corp. Consumer Goods Meat Products
MDT Medtronic, Inc. Healthcare Medical Appliances & Equipment
NTZ Natuzzi SpA Consumer Goods Home Furnishings & Fixtures
SIG Signet Jewelers Limited Services Jewelry Stores
VIP Vimpel-Communications Technology Wireless Communications
WH WSP Holdings Ltd. Basic Materials Oil & Gas Equipment & Services
WMG Warner Music Group Corp. Services Movie Production, Theaters
ZLC Zale Corporation Services Jewelry Stores
After close:
ASYS Amtech Systems Inc. Technology Semiconductor Equipment & Materials
BCSI Blue Coat Systems Inc. Technology Business Software & Services
CWTR Coldwater Creek Inc. Services Specialty Retail, Other
JCG J. Crew Group, Inc. Services Apparel Stores
JRJC China Finance Online Co. Ltd. Technology Internet Information Providers
NZ Netezza Corporation Technology Diversified Computer Systems
SNS Steak n Shake Co. Services Restaurants
TIVO TiVo Inc. Services CATV Systems
Monday, November 23, 2009
Market wrap - 4:10
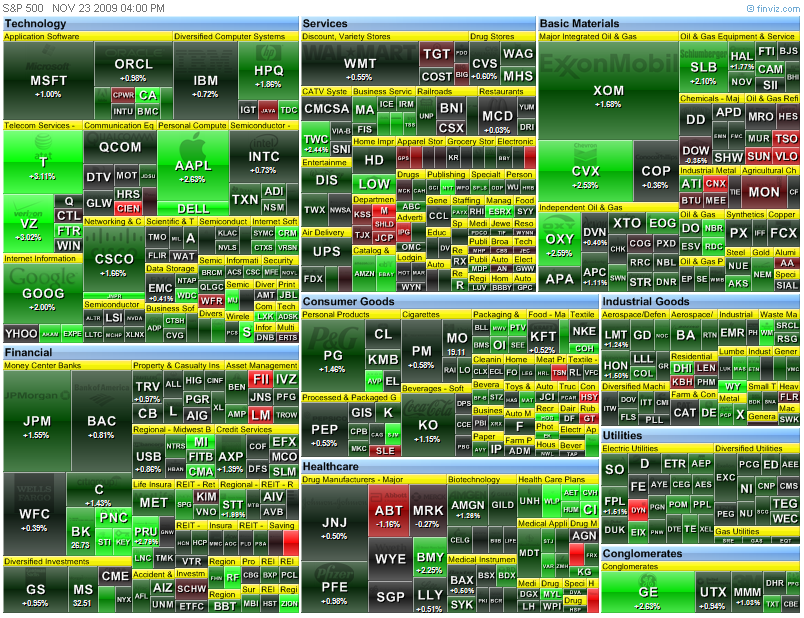
Large gap up, only to slowly go a bit lower as the dollar rose throughout the day.
Dow 10,451 133 1.29%
Nasdaq 2,176 30 1.40%
S&P 500 1,106 15 1.36%
Gold 1,165 +18 +1.57%
Oil 77.69 0.09 0.12%

Existing home sales - 10:00
Full report here
Washington, November 23, 2009
Driven by the first-time buyer tax credit, existing-home sales showed another big gain in October with a strong uptrend established over the past seven months, while inventories continue to decline, according to the National Association of Realtors®.
Existing-home sales – including single-family, townhomes, condominiums and co-ops – surged 10.1 percent to a seasonally adjusted annual rate1 of 6.10 million units in October from a downwardly revised pace of 5.54 million in September, and are 23.5 percent above the 4.94 million-unit level in October 2008. Sales activity is at the highest pace since February 2007 when it hit 6.55 million.
Lawrence Yun, NAR chief economist, was surprised at the size of the gain. “Many buyers have been rushing to beat the deadline for the first-time buyer tax credit that was scheduled to expire at the end of this month, and similarly robust sales may be occurring in November,” he said. “With such a sale spike, a measurable decline should be anticipated in December and early next year before another surge in spring and early summer.”
Now that the tax credit has been extended and expanded, potential buyers have until April 30 to have a contract in place. “There is still a large pent-up demand that can be tapped before the tax credit expires. Our recent consumer survey further shows that 13 percent of successful first-time buyers had a previous contract that was cancelled or fell through – there likely are many more buyers who were attempting to purchase but simply ran out of time,” Yun said.
Historically low interest rates also are boosting the market. “Mortgage interest rates last month were the third lowest on record dating back to 1971,” Yun noted. According to Freddie Mac, the national average commitment rate for a 30-year, conventional, fixed-rate mortgage fell to 4.95 percent in October from 5.06 percent in September; the rate was 6.20 percent in October 2008. Last week, Freddie Mac reporter the 30-year rate dropped to 4.83 percent.
NAR President Vicki Cox Golder, owner of Vicki L. Cox & Associates in Tucson, Ariz., said strong demand by first-time buyers is creating some unusual conditions. “In parts of the country, especially in Southwestern states but also in Florida and suburban Washington, D.C., we’ve been getting many reports of multiple bids in the lower price ranges with foreclosed properties getting absorbed quickly,” she said.
“In fact, low-end inventory has become very tight in many areas and in some cases buyers are becoming more aggressive. In this kind of environment it’s important to work with a Realtor® who can walk you through the process and help you negotiate a satisfactory deal,” Golder said.
Total housing inventory at the end of October fell 3.7 percent to 3.57 million existing homes available for sale, which represents a 7.0-month supply2 at the current sales pace, down from an 8.0-month supply in September. Unsold inventory totals are 14.9 percent below a year ago.
“The supply of homes on the market is now at the lowest level in over two-and-a half years – we’re getting closer to a general balance between buyers and sellers,” Yun said. The last time the relative housing inventory was this low was in February 2007 when it also was at a 7.0-month supply.
The national median existing-home price3 for all housing types was $173,100 in October, down 7.1 percent from October 2008. Distressed properties, which accounted for 30 percent of sales in October, continue to downwardly distort the median price because they usually sell at a discount relative to traditional homes in the same area.
“In the second half of 2010, if home values show consistent stabilization or even a modest increase, then home sales could remain at normal healthy levels because consumers would no longer be worried about a price overcorrection,” Yun said.
He added that low home prices also are contributing to extremely favorable affordability conditions. “With the abnormal drop in home prices over the past few years, the price-to-income ratio has fallen below the historic trend line,” Yun said. “This is adding to the buying power of the typical family, with affordability conditions this year at the highest on record dating back to 1970, but prices are beginning to flatten and are poised to rise next year.”
Single-family home sales rose 9.7 percent to a seasonally adjusted annual rate of 5.33 million in October from a pace of 4.86 million in September, and are 21.4 percent above the 4.39 million-unit pace in October 2008. The median existing single-family home price was $173,100 in October, down 6.8 percent from a year ago.
Existing condominium and co-op sales surged 13.2 percent to a seasonally adjusted annual rate of 770,000 units in October from 680,000 in September, and are 40.8 percent above the 547,000-unit level a year ago. The median existing condo price4 was $172,900 in October, which is 10.4 percent below October 2008.
Regionally, existing-home sales in the Northeast rose 11.6 percent to an annual level of 1.06 million in October, and are 27.7 percent higher than October 2008. The median price in the Northeast was $235,400, down 2.6 percent from a year ago.
Existing-home sales in the Midwest surged 14.4 percent in October to a pace of 1.43 million and are 28.8 percent above a year ago. The median price in the Midwest was $146,600, a gain of 1.1 percent from October 2008.
In the South, existing-home sales rose 12.7 percent to an annual level of 2.30 million in October and are 25.7 percent higher than October 2008. The median price in the South was $151,100, down 6.3 percent from a year ago.
Existing-home sales in the West increased 1.6 percent to an annual rate of 1.31 million in October and are 12.0 percent above a year ago. The median price in the West was $220,200, which is 14.7 percent below October 2008.
The National Association of Realtors®, “The Voice for Real Estate,” is America’s largest trade association, representing 1.2 million members involved in all aspects of the residential and commercial real estate industries.
Pre-market - Monday, November 23, 2009
Futures up big on a declining dollar.
DJIA INDEX 10,395.00 92.00
S&P 500 1,100.70 10.60
NASDAQ 100 1,779.25 15.75
Today's economic calendar:
Existing Home Sales 10:00 AM ET
4-Week Bill Announcement 11:00 AM ET
3-Month Bill Auction 11:30 AM ET
6-Month Bill Auction 11:30 AM ET
2-Yr Note Auction 1:00 PM ET
Today's earnings reports.
Before open:
BJS BJ Services Company Basic Materials Oil & Gas Equipment & Services
CDCS CDC Software Corporation Technology Application Software
CPB Campbell Soup Co. Consumer Goods Processed & Packaged Goods
JOBS 51job Inc. Services Staffing & Outsourcing Services
LDK LDK Solar Co.Ltd. Technology Diversified Electronics
NED Noah Education Holdings, Ltd. Services Publishing - Books
TECD Tech Data Corp. Services Computers Wholesale
TSN Tyson Foods Inc. Consumer Goods Meat Products
VAL Valspar Corp. Industrial Goods General Building Materials
After close:
ADI Analog Devices Inc. Technology Semiconductor - Broad Line
ATW Atwood Oceanics Inc. Basic Materials Oil & Gas Drilling & Exploration
BRCD Brocade Communications Systems, Inc. Technology Data Storage Devices
CNTF China Techfaith Wireless Communication Technology Ltd. Technology Diversified Communication Services
CTRN Citi Trends Services Apparel Stores
DY Dycom Industries Inc. Industrial Goods Heavy Construction
FMCN Focus Media Holding Ltd. Services Advertising Agencies
GLAD Gladstone Capital Corporation Financial Diversified Investments
HAYN Haynes International Inc. Basic Materials Steel & Iron
HPQ Hewlett-Packard Company Technology Diversified Computer Systems
NBG National Bank of Greece SA Financial Foreign Money Center Banks
NCTY The9 Limited Services Gaming Activities
NUAN Nuance Communications, Inc. Technology Application Software
SBLK Star Bulk Carriers Corp. Services Shipping
VIMC Vimicro International Corp. Technology Semiconductor - Specialized
Friday, November 20, 2009
Pre-market - Friday, November 20, 2009
Futures down significantly on the big miss by Dell last night.
DJIA INDEX 10,256.00 -71.00
S&P 500 1,085.70 -8.60
NASDAQ 100 1,758.50 -11.75
Today's economic calendar: Nothing
Today's earnings reports.
Before open:
ANN AnnTaylor Stores Corp. Services Apparel Stores
CRMT America's Car-Mart Inc. Services Auto Dealerships
DHI DR Horton Inc. Industrial Goods Residential Construction
JOUT Johnson Outdoors Inc. Consumer Goods Sporting Goods
KIRK Kirkland's Inc. Services Home Furnishing Stores
MPR Met-Pro Corp. Industrial Goods Diversified Machinery
SJM The J. M. Smucker Company Consumer Goods Processed & Packaged Goods
After close:
None
Thursday, November 19, 2009
Market wrap - 4:20
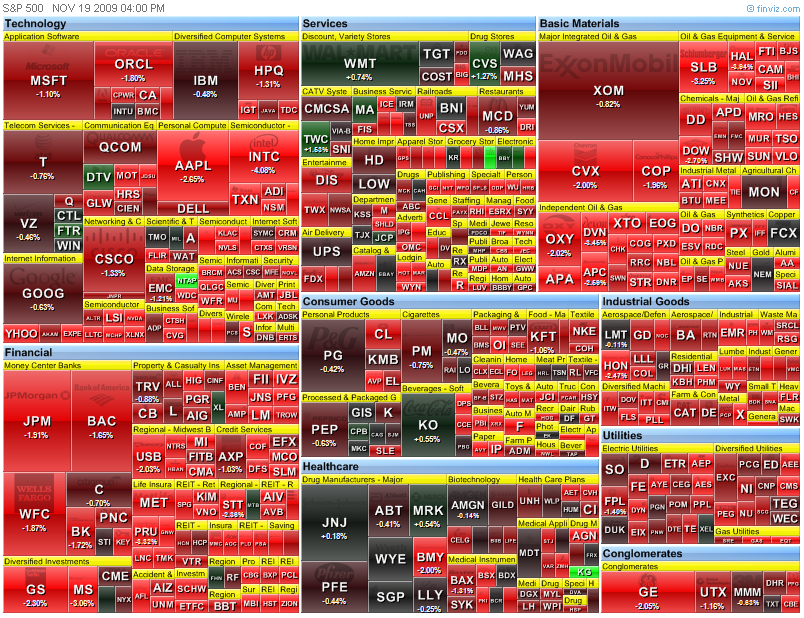
The market opened lower and continued the slide through much of the morning. The best show was congress talking to Geithner, and then the Paul/Grayson bill in the Finance committee. The market rose in the afternoon as the dollar fell.
Dow 10,333 -93 -0.89%
Nasdaq 2,157 -36 -1.65%
S&P 500 1,095 -15 -1.34%
Gold 1,142 +1 +0.09%
Oil 77.67 -2.12 -2.65%
Mortgage delinquencies hit record-high in 3Q - 10:45
From Yahoo & AP
Mortgage delinquencies hit record-high in 3Q
Delinquencies and foreclosures set 9th straight record in 3rd quarter as layoffs keep rising
* By Alan Zibel, AP Real Estate Writer
* On 10:05 am EST, Thursday November 19, 2009
WASHINGTON (AP) -- More than 14 percent of American homeowners with a mortgage were either behind on their payments or in foreclosure at the end of September, a record-high for the ninth straight quarter and a problem that could threaten the economic recovery.
The Mortgage Bankers Association's report Thursday adds to fears that the housing market and broader recovery could be thwarted by the continuing surge in home loan defaults, especially as the unemployment rate keeps rising. Lost jobs, rather than the shady loans made during the housing boom, are now the main reason homeowners fall behind on their mortgages.
After three years of plunging prices, the housing market started to rebound this summer. While optimists hope the worst is over, pessimists say there are simply too many foreclosed properties that have yet to be dumped on the market and expect further price declines.
About 4 million homeowners were either in foreclosure or at least three months behind on their mortgage payments as of September, according to the mortgage bankers group. Even if a quarter of those borrowers are able to stay in their homes, "there's a lot of potential inventory coming into the market next year," said Jay Brinkmann, chief economist with the Mortgage Bankers Association.
Those foreclosures will push home prices downward, especially in the hardest-hit California and Florida cities, places that are also coping with soaring unemployment, he said.
The record-high foreclosure numbers are being driven by borrowers with traditional fixed-rate mortgages, rather than the shady subprime loans with adjustable rates that kicked off the mortgage crisis.
Fixed-rate loans made to so-called prime borrowers with good credit histories caused nearly 33 percent of new foreclosures in the July-September quarter, compared with 21 percent a year ago.
Subprime loans with adjustable rates have fallen to 16 percent of new foreclosures from 35 percent a year earlier.
Loans backed by the Federal Housing Administration also show increasing signs of trouble. More than 18 percent of FHA borrowers are at least one payment behind or in foreclosure.
Among states, the worst of the trouble is still concentrated in California, Nevada, Arizona and Florida, which accounted for 44 percent of new foreclosures in the country. Nearly 13 percent of all loans in Florida were in foreclosure, the highest in the U.S., followed by Nevada at more than 9 percent.
Philly Fed - 10:00
Full report here
November 2009 Business Outlook Survey
Activity in the region's manufacturing sector is picking up, according to firms polled for this month's Business Outlook Survey. Indexes for general activity, new orders, and shipments all improved this month. The overall level of employment was mostly steady this month, and the average work hours index was positive for the first time in more than two years. The region's manufacturing executives expect increasing activity over the next six months, although expectations have moderated somewhat in the last several months. Low rates of current capacity utilization are suppressing capital spending plans.
Indicators Suggest Activity Is Picking Up
The survey's broadest measure of manufacturing conditions, the diffusion index of current activity, increased from a reading of 11.5 in October to 16.7 this month. The index has now remained positive for four consecutive months (see Chart). The percentage of firms reporting increases in activity this month (29 percent) exceeded the percentage reporting decreases (12 percent). Other broad indicators suggest similar improvement this month. The current new orders index also remained positive for the fourth consecutive month and increased nine points. The current shipments index increased 12 points. The current inventory index, although still negative, increased 15 points, from -31.8 in October to -17.3 this month. Indexes for unfilled orders and delivery times remained negative.
Labor market conditions have been stabilizing in recent months. The current employment index increased six points, from -6.8 to near zero. The percentage of firms reporting employment increases and decreases were essentially the same this month (14 percent). The workweek index edged seven points higher in November to its first positive reading in 23 months.
Prices of Manufactured Goods Are Near Steady
Recently reported declines in prices for manufactured goods were not as widespread this month. The prices received index increased three points, to -1.5, suggesting nearly steady prices for manufactured goods this month. Still, firms continue to report higher prices for purchased inputs. The prices paid index, which had been increasing for three consecutive months, fell back six points this month, to 14.9.
Manufacturers Are Generally Optimistic
The future general activity index remained positive for the 11th consecutive month but decreased from 39.8 in September to 36.8, its lowest reading since April (see Chart). Despite lower readings in recent months, indicators of future activity remain near levels not seen since 2004. Indexes for future new orders and shipments declined this month, falling five points and nine points, respectively. For the seventh consecutive month, the percentage of firms expecting employment to increase over the next six months exceeded the percentage expecting declines (27 percent versus 19 percent).
In this month's special questions, firms were asked about their current capacity utilization and capital spending plans (see Special Questions). Over 58 percent of the firms indicated that their current capacity utilization rate was less than 70 percent; only 8 percent of firms reported utilization rates lower than 70 percent before the beginning of the recession. The percentage of firms that indicated capital spending on plant and equipment would be lower next year (41 percent) substantially exceeded the percentage that indicated capital spending would be higher (16 percent). Firms indicated, on average, that capacity utilization would need to increase to nearly 84 percent before they would be inclined to increase spending to increase capacity at their plant.
Summary
According to respondents to the November Business Outlook Survey, manufacturing conditions are improving. The survey's indicators for general activity, new orders, and shipments were higher this month. Employment was nearly flat this month, and more firms reported an increase in work hours. Firms still expect continued improvement over the next six months, although future indicators suggest that optimism has waned somewhat in recent months. Capital spending plans are being held back by low plant utilization rates.
More at link with formatted tables
Leading indicators - 10:00
Full report here
Released: Thursday, November 19, 2009
The Conference Board Leading Economic Index™ (LEI) for the U.S. increased 0.3 percent in October, following a 1.0 percent gain in September, and a 0.4 percent rise in August.
Download a PDF of the technical notes for underlying detail, diffusion indexes, components, contributions and graphs.
Download a PDF of the press release with graph and summary table.
Says Ataman Ozyildirim, Economist at The Conference Board: “After half a year of consecutive increases, the month-to-month growth of the LEI is stabilizing and the gains continue to be broad-based. Meanwhile, the coincident economic index has been essentially flat since June, after declining since November 2007. The composite indexes suggest the recovery is unfolding and economic activity should continue improving in the near term.”
Says Ken Goldstein, Economist at The Conference Board: “The data indicates that economic recovery is finally setting in. We can expect slow growth through the first half of 2010. The pace of growth, however, will depend critically on how much demand picks up, and how soon.”
The Conference Board Coincident Economic Index™ (CEI) for the U.S. was unchanged in October, following a 0.1 percent decline in September, and a 0.1 percent increase in August. The Conference Board Lagging Economic Index™ (LAG) declined 0.2 percent in October, following a 0.5 percent decline in September, and a 0.4 percent decline in August.
The next release is scheduled for December 17, 2009 at 10 A.M. ET.
Interview with Elizabeth Warren on CNBC - 9:30
Pretty good interview with Elizabeth Warren on CNBC about TARP and the economy.
Jobless claims - 8:30 am
Full report here
UNEMPLOYMENT INSURANCE WEEKLY CLAIMS REPORT
SEASONALLY ADJUSTED DATA
In the week ending Nov. 14, the advance figure for seasonally adjusted initial claims was 505,000, unchanged from the previous week's revised figure of 505,000. The 4-week moving average was 514,000, a decrease of 6,500 from the previous week's revised average of 520,500.
The advance seasonally adjusted insured unemployment rate was 4.3 percent for the week ending Nov. 7, unchanged from the prior week's unrevised rate of 4.3 percent.
The advance number for seasonally adjusted insured unemployment during the week ending Nov. 7 was 5,611,000, a decrease of 39,000 from the preceding week's revised level of 5,650,000. The 4-week moving average was 5,711,500, a decrease of 83,500 from the preceding week's revised average of 5,795,000.
The fiscal year-to-date average for seasonally adjusted insured unemployment for all programs is 5.992 million.
UNADJUSTED DATA
The advance number of actual initial claims under state programs, unadjusted, totaled 479,295 in the week ending Nov. 14, a decrease of 53,132 from the previous week. There were 513,000 initial claims in the comparable week in 2008.
The advance unadjusted insured unemployment rate was 3.7 percent during the week ending Nov. 7, a decrease of 0.1 percentage point from the prior week. The advance unadjusted number for persons claiming UI benefits in state programs totaled 4,881,874, a decrease of 79,243 from the preceding week. A year earlier, the rate was 2.6 percent and the volume was 3,521,971.
Extended benefits were available in Alabama, Alaska, Arizona, California, Colorado, Connecticut, Delaware, the District of Columbia, Florida, Georgia, Idaho, Illinois, Indiana, Kansas, Kentucky, Maine, Massachusetts, Michigan, Minnesota, Missouri, Nevada, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Ohio, Oregon, Pennsylvania, Puerto Rico, Rhode Island, South Carolina, Tennessee, Texas, Vermont, Virginia, Washington, West Virginia, and Wisconsin during the week ending Oct. 31.
Initial claims for UI benefits by former Federal civilian employees totaled 2,331 in the week ending Nov. 7, a decrease of 62 from the prior week. There were 2,480 initial claims by newly discharged veterans, an increase of 199 from the preceding week.
There were 24,799 former Federal civilian employees claiming UI benefits for the week ending Oct. 31, an increase of 2,273 from the previous week. Newly discharged veterans claiming benefits totaled 34,919, an increase of 699 from the prior week.
States reported 3,622,091 persons claiming EUC (Emergency Unemployment Compensation) benefits for the week ending Oct. 31, an increase of 101,838 from the prior week. There were 772,645 claimants in the comparable week in 2008. EUC weekly claims include both first and second tier activity.
The highest insured unemployment rates in the week ending Oct. 31 were in Puerto Rico (6.1 percent), Oregon (5.5), Nevada (5.2), Alaska (5.0), California (5.0), Arkansas (4.9), Wisconsin (4.9), Michigan (4.8), Pennsylvania (4.8), and Washington (4.7).
The largest increases in initial claims for the week ending Nov. 7 were in Michigan (+6,001), New Jersey (+4,153), Pennsylvania (+3,552), New York (+3,508), and Ohio (+3,292), while the largest decreases were in Florida (-1,915), Arkansas (-734), Oregon (-274), South Carolina (-116), and West Virginia (-19).
More at link with formatted tables
Pre-market - Thursday - November 19, 2009
Futures down pretty good this morning. Important data to come out at 8:30.
DJIA INDEX 10,330.00 -74.00
S&P 500 1,098.10 -10.40
NASDAQ 100 1,785.75 -14.75
Today's economic reports:
Jobless Claims 8:30 AM ET
Leading Indicators 10:00 AM ET
Philadelphia Fed Survey 10:00 AM ET
EIA Natural Gas Report 10:30 AM ET
3-Month Bill Announcement 11:00 AM ET
6-Month Bill Announcement 11:00 AM ET
2-Yr Note Announcement 11:00 AM ET
5-Yr Note Announcement 11:00 AM ET
7-Yr Note Announcement 11:00 AM ET
Money Supply4:30 PM ET
Today's earnings reports.
Before open:
BKE Buckle Inc. Services Apparel Stores
BONT Bon-Ton Stores Inc. Services Department Stores
BRC Brady Corp. Services Business Services
CATO Cato Corp. Services Apparel Stores
CMED China Medical Technologies Inc. Healthcare Medical Instruments & Supplies
CMRG Casual Male Retail Group, Inc. Services Apparel Stores
DKS Dick's Sporting Goods Inc. Services Sporting Goods Stores
DWCH Datawatch Corp. Technology Business Software & Services
GME GameStop Corp. Services Electronics Stores
HP Helmerich & Payne Inc. Basic Materials Oil & Gas Drilling & Exploration
IGLD Internet Gold Golden Lines Ltd. Technology Diversified Communication Services
KLIC Kulicke & Soffa Industries Inc. Technology Semiconductor Equipment & Materials
NJR New Jersey Resources Corp. Utilities Gas Utilities
NWY New York & Company Inc. Services Apparel Stores
PDCO Patterson Companies Inc. Services Medical Equipment Wholesale
PLCE The Children's Place Retail Stores, Inc. Services Apparel Stores
RAVN Raven Industries Inc. Technology Printed Circuit Boards
ROST Ross Stores Inc. Services Apparel Stores
SBH Sally Beauty Holdings Inc. Services Specialty Retail, Other
SCHS School Specialty Inc. Services Wholesale, Other
SCMR Sycamore Networks Inc. Technology Networking & Communication Devices
SCVL Shoe Carnival Inc. Services Apparel Stores
SHLD Sears Holdings Corporation Services Department Stores
SI Siemens AG Technology Telecom Services - Foreign
SMRT Stein Mart Inc. Services Apparel Stores
SSI Stage Stores Inc. Services Apparel Stores
STP Suntech Power Holdings Co. Ltd. Technology Diversified Electronics
TDG TransDigm Group Incorporated Industrial Goods Aerospace/Defense Products & Services
TSL Trina Solar Ltd. Technology Semiconductor - Specialized
TWMC Trans World Entertainment Corporation Services Music & Video Stores
WSM Williams-Sonoma Inc. Services Home Furnishing Stores
After market closes:
ADCT ADC Telecommunications Inc. Technology Communication Equipment
APWR A-Power Energy Generation Systems, Ltd. Utilities Electric Utilities
ARUN Aruba Networks, Inc. Technology Computer Peripherals
BAMM Books-A-Million Inc. Services Specialty Retail, Other
CENT Central Garden & Pet Co. Services Wholesale, Other
CHRD Chordiant Software, Inc. Technology Technical & System Software
DBRN Dress Barn Inc. Services Apparel Stores
DELL Dell Inc. Technology Personal Computers
EFUT e-Future Information Technology Inc. Technology Business Software & Services
FL Foot Locker Inc. Services Apparel Stores
GFF Griffon Corporation Industrial Goods General Building Materials
GPS Gap Inc. Services Apparel Stores
HIBB Hibbett Sports, Inc. Services Sporting Goods Stores
INTU Intuit Inc. Technology Application Software
MTSC MTS Systems Corp. Technology Scientific & Technical Instruments
OHB Orleans Homebuilders Inc. Industrial Goods Residential Construction
OMER Omeros Corporation Healthcare Drug Manufacturers - Major
TSCM TheStreet.com, Inc. Technology Internet Information Providers
VRGY Verigy, Ltd. Technology Semiconductor Equipment & Materials
WTSLA Wet Seal Inc. Services Apparel Stores
ZUMZ Zumiez, Inc. Services Apparel Stores
Wednesday, November 18, 2009
Market wrap - 4:30
Just a slow no volume day - again.
Dow 10,426 -11 -0.11%
Nasdaq 2,193 -11 -0.48%
S&P 500 1,110 -1 -0.05%
Gold 1,141 +2 +0.17%
Oil 79.74 0.44 0.56%

Housing starts - 8:30
Full report here
NEW RESIDENTIAL CONSTRUCTION IN OCTOBER 2009
The U.S. Census Bureau and the Department of Housing and Urban Development jointly announced the following new residential construction statistics for October 2009:
BUILDING PERMITS
Privately-owned housing units authorized by building permits in October were at a seasonally adjusted annual rate of 552,000. This is 4.0 percent (±1.9%) below the revised September rate of 575,000 and is 24.3 percent (±1.9%) below the October 2008
estimate of 729,000. Single-family authorizations in October were at a rate of 451,000; this is 0.2 percent (±1.0%)* below the revised September figure of
452,000. Authorizations of units in buildings with five units or more were at a rate of 85,000 in October.
HOUSING STARTS
Privately-owned housing starts in October were at a seasonally adjusted annual rate of 529,000. This is 10.6 percent (±8.7%) below the revised September estimate of 592,000 and is 30.7 percent (±8.3%) below the October 2008 rate of 763,000. Single-family housing starts in October were at a rate of 476,000; this is 6.8 percent (±7.5%)* below the revised September figure of 511,000. The October rate for units in buildings with five units or more was 48,000.
HOUSING COMPLETIONS
Privately-owned housing completions in October were at a seasonally adjusted annual rate of 740,000. This is 1.9 percent (±12.4%)* above the revised September estimate of 726,000, but is 29.9 percent (±9.7%) below the October 2008 rate of 1,055,000.
Single-family housing completions in October were at a rate of 528,000; this is 10.7 percent (±14.5%)* above the revised September figure of 477,000. The October rate for units in buildings with five units or more was 200,000.
CPI - 8:30
Full report here
Consumer Price Index - October 2009
On a seasonally adjusted basis, the Consumer Price Index for All
Urban Consumers (CPI-U) rose 0.3 percent in October, the U.S. Bureau
of Labor Statistics reported today. The index has decreased 0.2
percent over the last 12 months on a not seasonally adjusted basis.
The seasonally adjusted all items increase largely reflected advances
in the indexes for energy and for new and used motor vehicles. The
energy index rose for the fifth time in the last six months,
advancing 1.5 percent as the indexes for gasoline, fuel oil, natural
gas, and electricity all increased. The index for all items less food
and energy rose 0.2 percent in October, the same increase as in
September. The indexes for used cars and trucks and for new vehicles
both rose sharply and together they accounted for over 90 percent of
the increase in the index for all items less food and energy. The
indexes for airline fares and medical care also increased, while the
shelter index was unchanged and the indexes for apparel and
recreation declined.
The food index also increased in October, rising 0.1 percent after
declining in two of the previous three months. The index for food
away from home increased slightly, while the food at home index was
unchanged. Within the food at home group, the index for dairy and
related products rose significantly, while the fruits and vegetables
index declined for the fourth straight month.
Consumer Price Index Data for October 2009
Food
The food index rose 0.1 percent in October after declining 0.1
percent in September. The index for food away from home increased 0.1
percent while the food at home index was unchanged. Within the food
at home group, the index for dairy and related products rose 1.0
percent in October after a 0.5 percent increase in September, and the
index for other food at home advanced 0.3 percent. These increases
were offset by a 0.7 percent decline in the fruits and vegetables
index and 0.2 percent decreases in the indexes for meats, poultry,
fish, and eggs and for nonalcoholic beverages. The index for cereals
and bakery products was unchanged in October. Over the past 12
months, the food index has declined 0.6 percent with the food at home
index down 2.8 percent.
Energy
The energy index rose 1.5 percent in October after increasing 0.6
percent in September. The index for energy commodities rose 1.9
percent, with the gasoline index increasing 1.6 percent. (Before
seasonal adjustment, gasoline prices fell 0.8 percent in October.)
The index for fuel oil rose 6.3 percent. The index for energy
services, which increased 0.1 percent in September, rose 0.9 percent
in October. The electricity index increased 0.6 percent while the
index for natural gas rose 1.9 percent in October after declining 1.7
percent in September. Over the past 12 months, the energy index has
fallen 14.0 percent with the gasoline index declining 17.9 percent.
All items less food and energy
The index for all items less food and energy rose 0.2 percent in
October, the same increase as in September. Most of the advance was
due to increases in transportation indexes. The new vehicles index
rose 1.6 percent and the index for used cars and trucks rose 3.4
percent, its third consecutive substantial increase. The index for
airline fares rose for the fourth straight month, increasing 1.7
percent in October. Outside of the transportation group, the changes
within all items less food and energy were largely modest. The
medical care index rose 0.2 percent in October after increasing 0.4
percent in September. The shelter index was unchanged in October, as
it was in September. The rent index decreased 0.1 percent, the index
for owners' equivalent rent was unchanged, and the index for lodging
away from home rose 0.4 percent. Posting declines in October were the
indexes for recreation and apparel, which both fell 0.4 percent. For
the past 12 months, the index for all items less food and energy has
risen 1.7 percent.
Not seasonally adjusted CPI measures
The Consumer Price Index for All Urban Consumers (CPI-U) decreased
0.2 percent over the last 12 months to an index level of 216.177
(1982-84=100). For the month, the index increased 0.1 percent prior
to seasonal adjustment.
The Consumer Price Index for Urban Wage Earners and Clerical Workers
(CPI-W) decreased 0.3 percent over the last 12 months to an index
level of 211.549 (1982-84=100). For the month, the index increased
0.1 percent prior to seasonal adjustment.
The Chained Consumer Price Index for All Urban Consumers (C-CPI-U)
decreased 0.5 percent over the last 12 months. For the month, the
index increased 0.1 percent on a not seasonally adjusted basis.
Please note that the indexes for the post-2007 period are subject to
revision.
More at link with formatted tables
Pre-market - 8:15
Futures up slightly this morning.
DJIA INDEX 10,409.00 11.00
S&P 500 1,108.80 1.40
NASDAQ 100 1,808.75 0.00
Today's economic reports:
MBA Purchase Applications 7:00 AM ET
Consumer Price Index 8:30 AM ET
Housing Starts 8:30 AM ET
EIA Petroleum Status Report 10:30 AM ET
Today's earnings reports:
Before open:
BJ BJ's Wholesale Club Inc. Services Discount, Variety Stores
CHS Chico's FAS Inc. Services Apparel Stores
CSUN China Sunergy Co. Ltd. Technology Semiconductor - Integrated Circuits
DHT DHT Maritime, Inc. Services Shipping
ESLT Elbit Systems Ltd. Industrial Goods Aerospace/Defense Products & Services
GU Gushan Environmental Energy Limited Basic Materials Specialty Chemicals
NM Navios Maritime Holdings Inc. Services Shipping
PERY Perry Ellis International Inc. Consumer Goods Textile - Apparel Clothing
SMLC 012 Smile.Communications Ltd. Technology Diversified Communication Services
SOLF Solarfun Power Holdings Co. Ltd. Technology Semiconductor - Specialized
VVTV ValueVision Media Inc. Services Catalog & Mail Order Houses
After close:
CYBX Cyberonics Inc. Healthcare Medical Appliances & Equipment
DCI Donaldson Company Inc. Industrial Goods Pollution & Treatment Controls
GYMB Gymboree Corp. Services Apparel Stores
HOTT Hot Topic Inc. Services Apparel Stores
JACK Jack in the Box Inc. Services Restaurants
LTD Limited Brands Inc. Services Apparel Stores
NTAP NetApp, Inc. Technology Data Storage Devices
NTES Netease.com Inc. Technology Internet Information Providers
PETM Petsmart Inc. Services Specialty Retail, Other
PNNT Pennantpark Investment Corp. Financial Diversified Investments
PVH Phillips-Van Heusen Corp. Consumer Goods Textile - Apparel Clothing
SMTC Semtech Corp. Technology Semiconductor - Integrated Circuits
WGOV Woodward Governor Co. Industrial Goods Industrial Electrical Equipment
Tuesday, November 17, 2009
Market wrap - late - 6:40
Pretty much a draw today between the Bears and the Bulls. Volume very low.
Dow 10,437 30 0.29%
Nasdaq 2,204 6 0.27%
S&P 500 1,110 1 0.09%
Gold 1,139 0 0.00%
Oil 79.40 +0.23 +0.29%
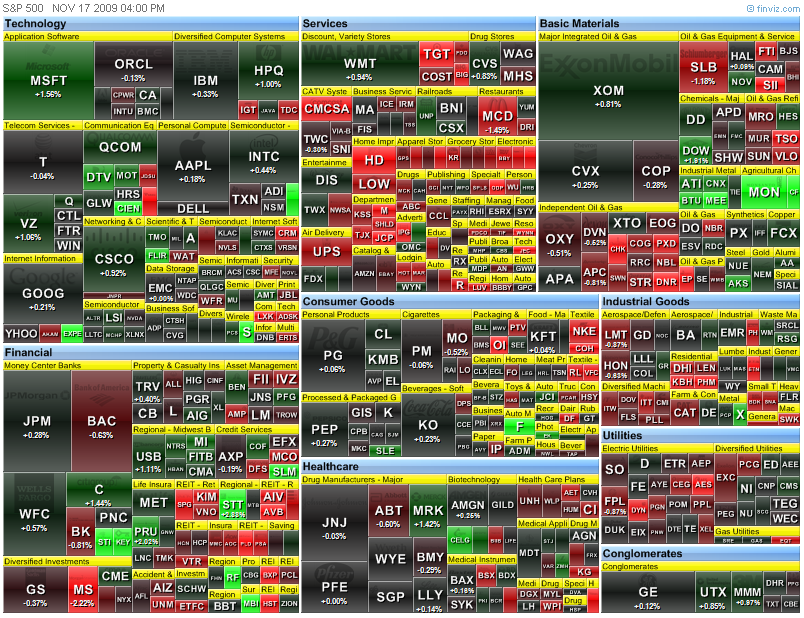
Producer price index - 8:30
Full report here
The Producer Price Index for Finished Goods advanced 0.3 percent in October, easonally adjusted, the U.S. Bureau of Labor Statistics reported today. This increase followed a 0.6-percent decline in September and a 1.7-percent rise in August. In October, at the earlier stages of processing, prices received by manufacturers of intermediate goods moved up 0.3 percent and the crude goods index increased 5.4 percent. On an unadjusted basis, from October 2008 to October 2009, prices for finished goods fell 1.9 percent, the eleventh consecutive month of year-over-year declines. (See table A.)
See link for table A
Finished goods
The October increase in the index for finished goods can be attributed to higher prices for energy and food, both of which moved up 1.6 percent. By contrast, prices for finished goods other than foods and energy declined 0.6 percent.
Finished energy: The index for finished energy goods advanced 1.6 percent in October compared with a 2.4-percent drop in the previous month. Almost half of the increase can be traced to the gasoline index, which climbed 1.9 percent. Rising prices for residential electric power and liquefied petroleum gas also contributed to the advance in the finished energy goods index. (See table 2.)
Finished foods: Finished consumer food prices rose 1.6 percent in October after edging down 0.1 percent a month earlier. Accounting for about half of the increase, the index for fresh and dry vegetables jumped 24.2 percent. Higher prices for fresh fruits and melons also contributed to the advance in the finished consumer foods index.
Finished core: In October, the index for finished goods less foods and energy moved down 0.6 percent, its second consecutive decrease. Lower prices for light motor trucks and passenger cars led the October decline, falling 5.2 percent and 0.5 percent, respectively. In accordance with usual practice, most new-model-year passenger cars and light motor trucks were introduced into the PPI in October. (See Report on Quality Changes for 2010 Model Vehicles, USDL 09-1400.)
Intermediate goods
The Producer Price Index for Intermediate Materials, Supplies, and Components moved up 0.3 percent in October, its third straight monthly advance. The October rise can be traced to higher prices for intermediate energy goods, which climbed 2.3 percent. By contrast, the indexes for both intermediate goods less foods and energy and for intermediate foods and feeds decreased 0.2 percent. On a 12-month basis, prices for intermediate goods fell 7.5 percent in October. This is the third consecutive month of slowing year-over-year declines following a record 15.1-percent drop for the 12 months ended July 2009. (See table B.)
Intermediate energy: The index for intermediate energy goods advanced 2.3 percent in October after falling 2.1 percent in September. About one-fifth of this increase can be traced to a 5.5-percent rise in diesel fuel prices. Higher prices for natural gas to electric utilities and commercial electric power also contributed to the advance in the intermediate energy goods index. (See table 2.)
Crude goods
The Producer Price Index for Crude Materials for Further Processing increased 5.4 percent in October after falling 2.1 percent in September. For the 3-month period ending in October, crude material prices rose 7.1 percent after advancing 4.1 percent in the 3 months ending in July. The monthly October rise was broad based, with prices for crude energy materials jumping 8.3 percent, the index for crude foodstuffs and feedstuffs moving up 5.2 percent, and prices for crude nonfood materials less energy increasing 0.5 percent. (See table B.)
Crude energy: The index for crude energy materials increased 8.3 percent in October. From July to October, this index rose 9.5 percent, compared with an 11.8-percent rise in the 3 months ending in July. Accounting for about sixty percent of the monthly October increase, the natural gas index moved up 16.3 percent. Higher prices for both crude petroleum and coal also contributed to the advance in the crude energy materials index. (See table 2.)
Crude foods: The index for crude foodstuffs and feedstuffs increased 5.2 percent in October. This index moved up 2.4 percent in the most recent 3-month period compared with a 6.0-percent decline in the previous 3-month period. In October, a 9.0-percent rise in the grains index led the advance in the crude foodstuffs and feedstuffs index. Higher prices for slaughter poultry were also a factor in this increase.
Crude core: The index for crude nonfood materials less energy rose 0.5 percent in October, and 10.4 percent for the 3 months ending in October. Similarly, for the 3 months ending in July, prices climbed 10.8 percent. A major contributor to the monthly October increase was the gold ores index, which rose 5.4 percent.
See link for table B
Services Analysis
Trade industries: The Producer Price Index for the Net Output of Total Trade Industries was unchanged in October after falling in each of the previous three months. (Trade indexes measure changes in margins received by wholesalers and retailers.) In October, higher margins received by merchant wholesalers of nondurable goods and new car dealers were offset by lower margins received by merchant wholesalers of durable goods and gasoline stations with convenience
stores.
Transportation and warehousing industries: The Producer Price Index for the Net Output of Total Transportation and Warehousing Industries moved up 0.6 percent in October following a 0.7-percent decline in September. About two-thirds of this advance can be attributed to a 2.8-percent increase in prices received by the industry for scheduled passenger air transportation. The industry indexes for couriers and line-haul railroads also rose in October.
Traditional service industries: The Producer Price Index for the Net Output of Total
Traditional Service Industries advanced 0.5 percent in October after declining 0.2 percent in September. Leading this upturn, prices received by the commercial banking industry moved up 2.0 percent. The industry indexes for general medical and surgical hospitals and for investment banking and securities dealing also advanced in October.
Pre-market - Tuesday, November 17, 2009
Futures flat this morning on a rise in the dollar.
DJIA INDEX 10,363.00 -5.00
S&P 500 1,105.60 -0.70
NASDAQ 100 1,802.50 -1.00
ICSC-Goldman Store Sales 7:45 AM ET
Producer Price Index 8:30 AM ET
Redbook 8:55 AM ET
Treasury International Capital 9:00 AM ET
Industrial Production 9:15 AM ET
Jeffrey Lacker Speaks 10:00 AM ET
4-Week Bill Auction 11:30 AM ET
52-Week Bill Auction 11:30 AM ET
Housing Market Index 1:00 PM ET
Today's earnings reports:
ATV Acorn International, Inc. Services Catalog & Mail Order Houses
COV Covidien plc Healthcare Medical Instruments & Supplies
CPSL China Precision Steel, Inc. Basic Materials Steel & Iron
CSIQ Canadian Solar Inc. Technology Semiconductor - Specialized
DDS Dillard's Inc. Services Department Stores
EDAP EDAP TMS SA Healthcare Medical Appliances & Equipment
GASS StealthGas, Inc. Services Shipping
HD The Home Depot, Inc. Services Home Improvement Stores
ITRN Ituran Location & Control Ltd. Services Electronics Wholesale
JEC Jacobs Engineering Group Inc. Services Technical Services
JST Jinpan International Ltd. Technology Diversified Electronics
KEI Keithley Instruments Inc. Technology Scientific & Technical Instruments
MPEL Melco Crown Entertainment Ltd. Services Resorts & Casinos
SKS Saks Incorporated Services Department Stores
TGT Target Corp. Services Discount, Variety Stores
TJX The TJX Companies, Inc. Services Department Stores
WX WuXi PharmaTech (Cayman) Inc. Healthcare Drug Manufacturers - Major
After close:
ADSK Autodesk, Inc. Technology Technical & System Software
ALOT Astro-Med Inc. Technology Computer Peripherals
CNQR Concur Technologies, Inc. Technology Technical & System Software
CRM Salesforce.com Technology Application Software
DL China Distance Education Holdings Limited Services Education & Training Services
EJ E-House (China) Holdings Limited Financial Property Management
HNSN Hansen Medical, Inc. Healthcare Medical Appliances & Equipment
LZB La-Z-Boy Inc. Consumer Goods Home Furnishings & Fixtures
PCYO Pure Cycle Corp. Industrial Goods Heavy Construction
PLNR Planar Systems Inc. Technology Computer Peripherals
SNS Steak n Shake Co. Services Restaurants
VIT VanceInfo Technologies Inc. Technology Business Software & Services
Monday, November 16, 2009
Market wrap - 4:10
The rally today started at the open and ran up all day. At the same time, the dollar was falling. Until late in the day, the dollar turned around a bit, but it finding the 75 level as resistance now, and not support. As the dollar goes, so goes the market. Trade accordingly.
Dow 10,406 +136 +1.32%
Nasdaq 2,198 30 1.38%
S&P 500 1,109 16 1.45%
Gold 1,139 +23 +2.03%
Oil 78.81 2.55 3.34%
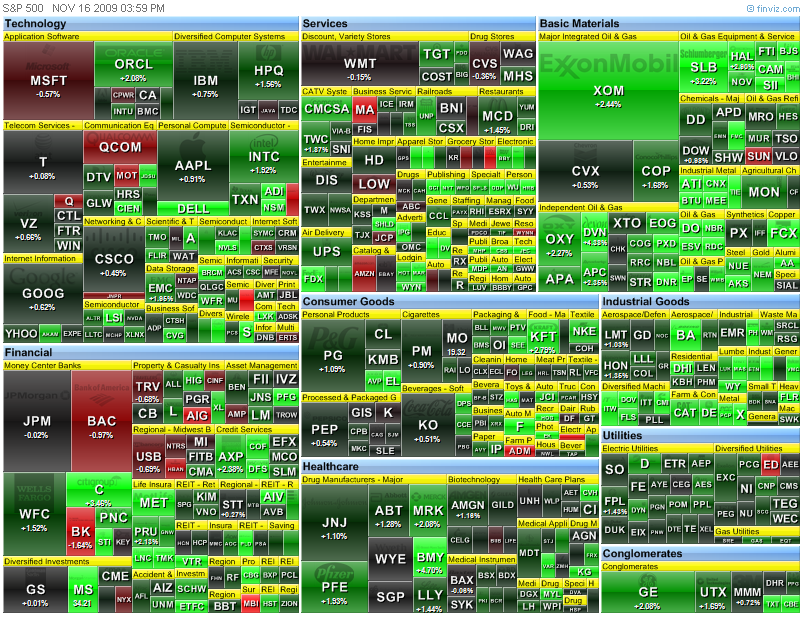
I hope to have a Meredith Whitney and a Peter Shiff interview once they get posted on CNBC. The Whitney interview is a must see, but Shiff is on Fast Money so I'm confident they will screw it up. They are perma bull pump monkey's and Shiff is a perma bear. Fast Money does have the ability to shut you off, and they most certainly will on Shiff.
I hope to have a Meredith Whitney and a Peter Shiff interview once they get posted on CNBC. The Whitney interview is a must see, but Shiff is on Fast Money so I'm confident they will screw it up. They are perma bull pump monkey's and Shiff is a perma bear. Fast Money does have the ability to shut you off, and they most certainly will on Shiff.
Business inventories - 10:00
Full report here
 MANUFACTURING AND TRADE INVENTORIES AND SALES
September 2009
Sales. The U.S. Census Bureau announced today that the combined value of distributive trade sales and manufacturers’ shipments for September, adjusted for seasonal and trading-day differences but not for price changes, was estimated at $988.0 billion, down 0.3 percent (±0.3%)* from August 2009 and down 13.1 percent (±0.6%) from September 2008.
Inventories. Manufacturers’ and trade inventories, adjusted for seasonal variations but not for price changes, were estimated at an end-of-month level of $1,303.4 billion, down 0.4 percent (±0.1%) from August 2009 and down 13.4 percent (±0.3%) from September 2008.
Inventories/Sales Ratio. The total business inventories/sales ratio based on seasonally adjusted data at the end of September was 1.32. The September 2008 ratio was 1.32.
MANUFACTURING AND TRADE INVENTORIES AND SALES
September 2009
Sales. The U.S. Census Bureau announced today that the combined value of distributive trade sales and manufacturers’ shipments for September, adjusted for seasonal and trading-day differences but not for price changes, was estimated at $988.0 billion, down 0.3 percent (±0.3%)* from August 2009 and down 13.1 percent (±0.6%) from September 2008.
Inventories. Manufacturers’ and trade inventories, adjusted for seasonal variations but not for price changes, were estimated at an end-of-month level of $1,303.4 billion, down 0.4 percent (±0.1%) from August 2009 and down 13.4 percent (±0.3%) from September 2008.
Inventories/Sales Ratio. The total business inventories/sales ratio based on seasonally adjusted data at the end of September was 1.32. The September 2008 ratio was 1.32.
Retail Sales - 8:30
Full report here
The U.S. Census Bureau announced today that advance estimates of U.S. retail and food services sales for October, adjusted for seasonal variation and holiday and trading-day differences, but not for price changes, were $347.5 billion, an increase of 1.4 percent (±0.5%) from the previous month, but 1.7 percent (±0.5%) below October 2008. Total sales for the August through October 2009 period were up 1.5 percent (±0.3%) from the same period a year ago. The August to September 2009 percent change was revised from -1.5 percent (±0.5%) to -2.3 percent (±0.3%).
Retail trade sales were up 1.4 percent (±0.7%) from September 2009, but 2.1 percent (±0.5%) below last year. Gasoline stations sales were down 15.0 percent (±1.3%) from October 2008 and building material and garden equipment and supplies dealers were down 15.0 percent (±1.8%) from last year.
More info at link with formatted tables
Pre-market - Monday, November 16,2009
Futures up on good news out of Japan.
DJIA INDEX 10,310.00 68.00
S&P 500 1,100.60 9.20
NASDAQ 100 1,798.25 10.00
Today's economic calendar:
Retail Sales 8:30 AM ET
Empire State Mfg Survey 8:30 AM ET
Business Inventories 10:00 AM ET
4-Week Bill Announcement 11:00 AM ET
3-Month Bill Auction 11:30 AM ET
6-Month Bill Auction 11:30 AM ET
Ben Bernanke Speaks 12:00 PM ET
Today's earnings reports:
Before market opens:
ADES ADA-ES, Inc. Industrial Goods Pollution & Treatment Controls
ADY American Dairy Inc. Consumer Goods Dairy Products
CAEI China Architectural Engineering, Inc. Industrial Goods General Contractors
COWN Cowen Group Inc. Financial Investment Brokerage - National
CYPB Cypress Bioscience, Inc. Healthcare Biotechnology
ESEA Euroseas, Ltd. Services Shipping
FLML Flamel Technologies SA Healthcare Drug Delivery
FREE FreeSeas Inc. Services Shipping
FTK Flotek Industries Inc. Basic Materials Specialty Chemicals
HAST Hastings Entertainment Inc. Services Music & Video Stores
KHD KHD Humboldt Wedag International Ltd. Services Industrial Equipment Wholesale
LOW Lowe's Companies Inc. Services Home Improvement Stores
NSSC Napco Security Technologies, Inc. Services Security & Protection Services
ORBK Orbotech Ltd. Technology Scientific & Technical Instruments
PWRD Perfect World Co., Ltd. Technology Application Software
SCR Simcere Pharmaceutical Group. Healthcare Drug Manufacturers - Other
SIHI SinoHub, Inc. Services Electronics Wholesale
SOL ReneSola Ltd. Technology Semiconductor - Integrated Circuits
WX WuXi PharmaTech (Cayman) Inc. Healthcare Drug Manufacturers - Major
ZSTN ZST Digital Networks, Inc. Technology Communication Equipment
After market closes:
ADAT Authentidate Holding Corp. Technology Internet Software & Services
ADG Allied Defense Group Inc. Industrial Goods Aerospace/Defense Products & Services
AGO Assured Guaranty Ltd. Financial Life Insurance
AOB American Oriental Bioengineering Inc. Healthcare Biotechnology
CDCS CDC Software Corporation Technology Application Software
CHINA CDC Corp. Technology Internet Software & Services
DMC Document Security Systems Inc. Services Security & Protection Services
ERI Emrise Corp. Industrial Goods Aerospace/Defense Products & Services
FC Franklin Covey Co. Consumer Goods Office Supplies
FMCN Focus Media Holding Ltd. Services Advertising Agencies
LFT Longtop Financial Technologies Limited Technology Business Software & Services
NAK Northern Dynasty Minerals Ltd. Basic Materials Gold
PSUN Pacific Sunwear of California Inc. Services Apparel Stores
RGDX Response Genetics, Inc Healthcare Diagnostic Substances
SINA Sina Corp. Technology Internet Software & Services
SPRD Spreadtrum Communications Inc. Technology Semiconductor - Broad Line
ZOOM ZOOM Technologies Inc. Technology Communication Equipment
Subscribe to:
Posts (Atom)
